What Is the Break Even Point Formula for Service Business?
Many service businesses stay busy but still struggle to make money. A full calendar does not always mean a healthy business. If your pricing does not cover your operating costs, every new project can add work without improving your bottom line.
Learning the break even point formula for service business helps you understand the minimum amount of work your business must complete before it starts making a profit. Whether you bill by the hour, charge fixed project fees, or work on monthly retainers, knowing your break-even point gives you a clear financial target.
In this guide, you’ll learn:
- What a break-even point means for a service business
- Why traditional product-based formulas often produce misleading results
- How to calculate your break-even point using billable hours, retainers, and fixed-price projects
- Common mistakes that can distort your numbers
- Practical examples you can apply to your own business
By the end, you’ll have a simple method for setting pricing, planning capacity, and making more informed financial decisions.
What Is a Break-Even Point?
A break-even point is the point where your total income equals your total business costs. At this stage, your business is not making a profit, but it is not operating at a loss either.
For service businesses, this means your client revenue is enough to pay for every fixed and variable expense.
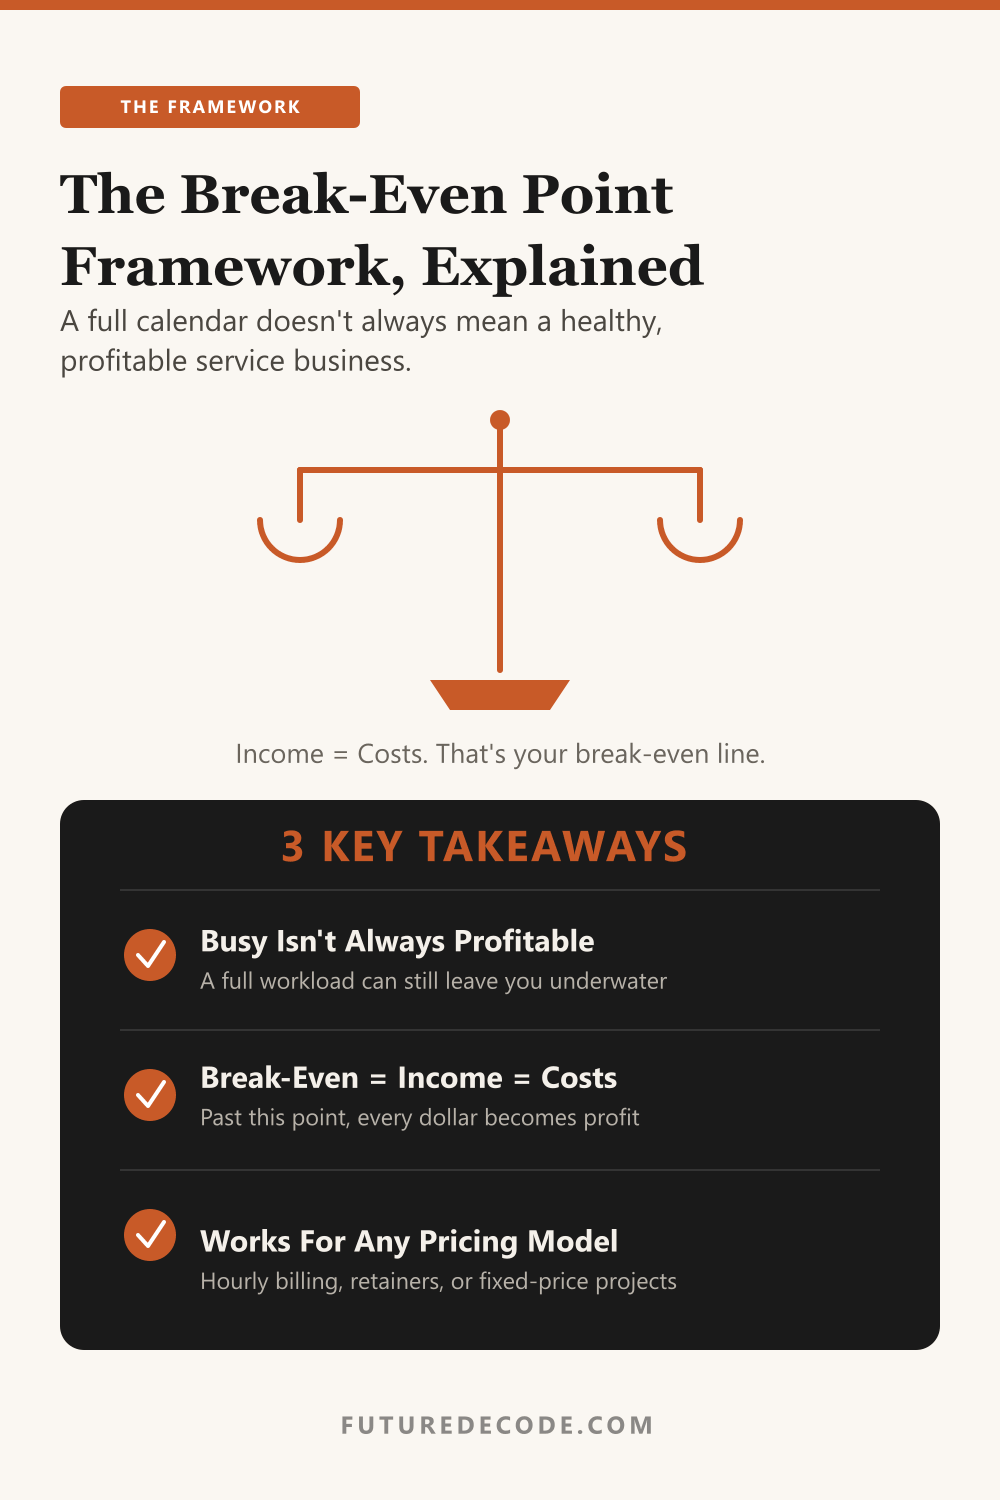
Once you earn more than your break-even point, each additional dollar contributes toward profit.
Think of it as your monthly financial target. Before reaching it, your revenue covers expenses. After reaching it, your business begins generating earnings.
Why Every Service Business Should Know Its Break-Even Point
Many owners focus on revenue alone. Revenue is important, but it does not reveal whether the business is actually making money.
Understanding your break-even point helps you answer questions such as:
- How many hours should I bill each month?
- How many clients do I need?
- Should I increase my prices?
- Can I afford another employee?
- Will a new software subscription pay for itself?
Without these answers, pricing decisions often rely on guesswork instead of financial data.
Understanding the Costs Behind the Formula
Before using the break even point formula for service business, you need to understand the numbers that go into it.
Fixed Costs
Fixed costs stay relatively the same each month, regardless of how many clients you serve.
Common examples include:
- Office rent
- Administrative salaries
- Insurance
- Accounting fees
- Software subscriptions
- Loan repayments
- Internet and phone services
Example
A small bookkeeping company might have monthly fixed costs like these:
| Expense | Monthly Cost |
|---|---|
| Office rent | $2,000 |
| Administrative salary | $4,500 |
| Software | $900 |
| Insurance | $600 |
| Loan payment | $1,500 |
| Total Fixed Costs | $9,500 |
These expenses must be paid whether the business serves 5 clients or 50 clients.
Variable Costs
Variable costs increase only when work is completed.
Examples include:
- Contractor payments
- Payment processing fees
- Project-specific software
- Travel expenses
- Materials purchased for a client project
If you do not perform the work, these costs usually do not occur.
Contribution Margin
Contribution margin is one of the most important numbers in break-even analysis.
It represents the amount of revenue remaining after direct variable costs have been deducted.
The remaining amount is used to pay fixed costs.
After fixed costs are covered, any remaining contribution becomes profit.
Formula
Contribution Margin = Selling Price − Variable Costs
Example
| Item | Amount |
|---|---|
| Hourly billing rate | $180 |
| Variable costs | $40 |
| Contribution margin | $140 |
This means every billable hour contributes $140 toward covering overhead before generating profit.
Understanding Billable Capacity
Service businesses sell time, knowledge, and expertise instead of physical products.
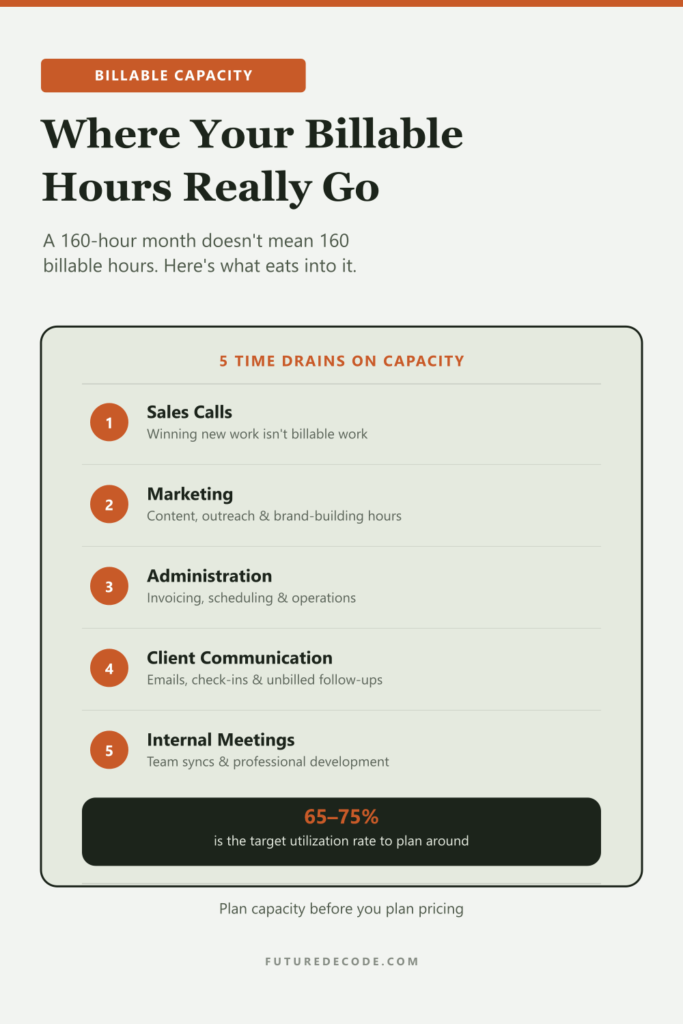
That makes capacity just as important as pricing.
For example, a consultant working 160 hours each month cannot realistically bill all 160 hours to clients.
Time is also spent on:
- Sales calls
- Marketing
- Administration
- Client communication
- Professional development
- Internal meetings
Many successful service businesses target a utilization rate between 65% and 75%. This provides enough billable work while leaving time to run the business effectively.
Why Traditional Break-Even Formulas Often Fail Service Businesses
Many articles explain break-even analysis using manufacturing examples.
Those examples assume every product has:
- A standard selling price
- A consistent production cost
- Physical inventory
- Unlimited production capacity
Service businesses operate differently.
Instead of selling products, they sell expertise, time, and client outcomes.
This creates several challenges that traditional examples rarely address.
1. There Is No Physical Inventory
A lawyer, consultant, accountant, or marketing agency cannot store today’s work and sell it next month.
Unused time is lost forever.
2. Capacity Is Limited
A factory can often increase production by running another shift.
A service business is limited by the available working hours of its team.
Once those hours are full, additional growth usually requires hiring staff, increasing prices, or improving efficiency.
3. Labour Is Both a Cost and an Asset
In many service businesses, employee wages represent the largest expense.
Some labour is fixed, while other labour changes with each project.
Understanding this difference is essential when calculating contribution margins accurately.
4. Scope Changes Affect Profitability
Projects often grow beyond their original agreement.
If extra work is completed without additional billing, your contribution margin becomes smaller and your actual break-even point increases.
5. Cash Flow Does Not Always Match Profit
A business may appear profitable on paper while still struggling to pay its bills.
Late client payments, loan repayments, and tax obligations all affect cash flow.
For this reason, many owners monitor both their accounting break-even point and their cash break-even point.
HOW TO CALCULATE THE BREAK EVEN POINT FORMULA FOR SERVICE BUSINESS
Now that you understand the financial terms, it’s time to calculate your break-even point.
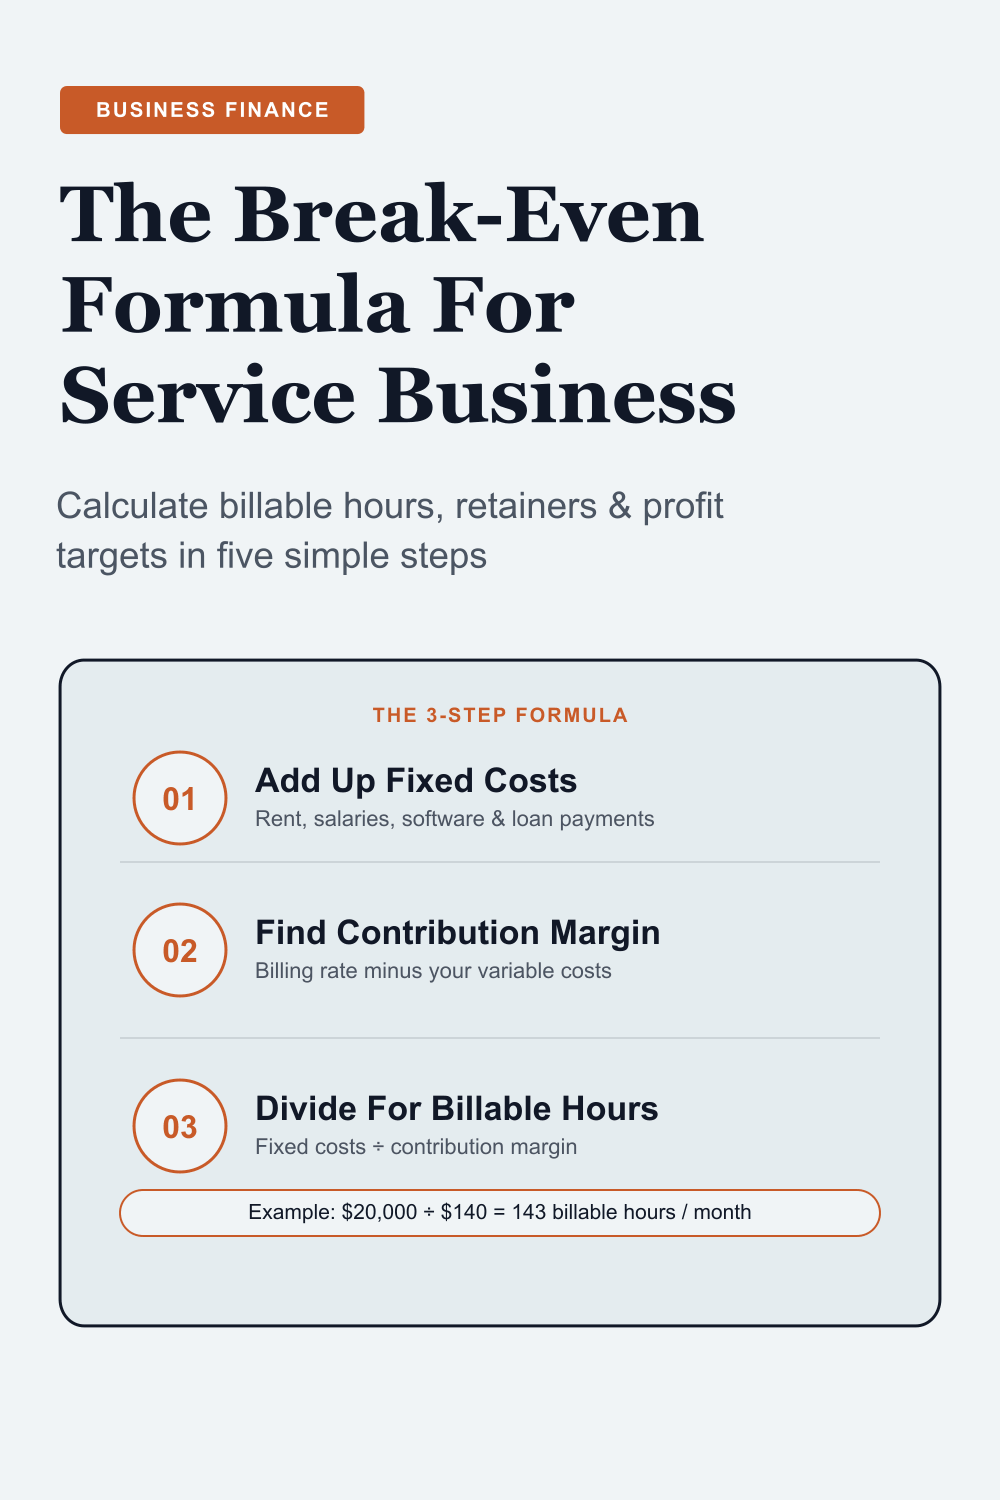
The process is simpler than many business owners expect. Once you’ve gathered your monthly costs and pricing information, you can calculate the minimum amount of work needed before your business earns a profit.
Break Even Point Formula for Service Business
For businesses that charge by the hour, use this formula:
Required Billable Hours =
Total Fixed Costs ÷ Hourly Contribution Margin
If you want the calculation to include your target salary, use:
Required Billable Hours =
(Total Fixed Costs + Owner Compensation)
÷
Hourly Contribution Margin
This version gives a more realistic financial target because it treats your income as part of the business requirements instead of an afterthought.
Step 1: Calculate Your Total Monthly Fixed Costs
Start by listing every expense that stays relatively consistent each month.
Typical fixed costs include:
- Office rent
- Administrative wages
- Insurance
- Accounting services
- Software subscriptions
- Internet and phone
- Equipment leases
- Loan repayments
- Owner salary (recommended)
Example
A small consulting business has the following monthly expenses.
| Expense | Monthly Cost |
|---|---|
| Office rent | $2,500 |
| Administrative support | $4,000 |
| Software subscriptions | $1,200 |
| Insurance | $800 |
| Loan repayments | $1,500 |
| Owner salary | $10,000 |
| Total Fixed Costs | $20,000 |
This means the business must recover $20,000 before making any profit.
💡 Tip: Divide annual expenses such as insurance renewals or software licences by 12 so they are included in your monthly calculation.
Step 2: Calculate Your Hourly Contribution Margin
Next, determine how much money each billable hour contributes toward paying your overhead.
Use this formula:
Contribution Margin =
Hourly Billing Rate − Variable Cost Per Hour
Only include costs that occur because client work is performed.
Examples include:
- Contractor wages
- Project software
- Payment processing fees
- Travel expenses
- Client-specific materials
Worked Example
A management consultant charges:
- Hourly rate: $180
- Contractor support: $25
- Software allocation: $10
- Payment fees: $5
Variable costs total $40.
Calculation:
$180 − $40 = $140The hourly contribution margin is:
$140 per billable hour
Every additional hour billed contributes $140 toward fixed costs until the business reaches break-even.
Step 3: Calculate Required Billable Hours
Now divide your fixed costs by your contribution margin.
Formula
Required Billable Hours =
Total Fixed Costs ÷ Contribution Margin
Example
Fixed Costs:
$20,000
Contribution Margin:
$140
Calculation:
20,000 ÷ 140 = 142.86Round up because partial billable hours rarely represent practical monthly targets.
Result
The business needs approximately:
143 billable hours per month
before generating profit.
Step 4: Convert Monthly Targets into Weekly Goals
Large monthly numbers can feel difficult to manage.
Breaking them into weekly targets makes planning much easier.
Formula:
Weekly Target =
Monthly Billable Hours ÷ 4.33
Example:
143 ÷ 4.33 = 33 hoursYour operational goal becomes:
Approximately 33 billable hours each week.
This target is much easier to monitor than waiting until month-end.
Step 5: Check Whether Your Capacity Is Realistic
Your calculation only works if your team has enough available capacity.
Suppose your business has:
- 2 consultants
- Each works 160 hours monthly
Total available hours:
2 × 160 = 320 hoursRequired billable hours:
143
Utilization Formula:
143 ÷ 320 × 100Result:
44.7% utilization
This is comfortably below the recommended operating range.
If your calculation required 290 billable hours, utilization would exceed 90%, leaving little time for administration, sales, or unexpected work.
That usually signals a pricing or staffing problem.
Quick Financial Summary
| Metric | Result |
|---|---|
| Monthly fixed costs | $20,000 |
| Hourly billing rate | $180 |
| Variable costs | $40 |
| Contribution margin | $140 |
| Required billable hours | 143 |
| Weekly target | 33 hours |
| Team utilization | 44.7% |
Example 1: Break-Even for Monthly Retainers
Many agencies and professional firms earn recurring monthly revenue instead of billing by the hour.
The process is almost identical.
Formula
Required Clients =
Total Fixed Costs
÷
Contribution Margin Per Client
Example
A digital marketing agency has:
| Item | Amount |
|---|---|
| Monthly overhead | $18,000 |
| Monthly retainer | $3,000 |
| Delivery costs | $600 |
Contribution Margin:
3,000 − 600 = 2,400Required Clients:
18,000 ÷ 2,400 = 7.5Round up.
The agency needs:
8 active retainer clients
to break even.
Monthly revenue required:
8 × 3,000 = 24,000Revenue target:
$24,000 per month
Example 2: Break-Even for Fixed-Price Projects
Some businesses charge a fixed fee for every project.
Examples include:
- Architects
- Engineers
- Web designers
- Accountants
- Business consultants
Suppose an engineering firm has:
| Item | Amount |
|---|---|
| Monthly fixed costs | $30,000 |
| Project fee | $5,000 |
| Variable costs | $1,250 |
Contribution Margin:
5,000 − 1,250 = 3,750Projects Required:
30,000 ÷ 3,750 = 8The business must complete:
8 projects each month
before earning a profit.
Revenue Target:
8 × 5,000 = 40,000Required monthly revenue:
$40,000
Key Takeaway
Every service business should know at least 3 numbers:
✅ Monthly fixed costs
✅ Contribution margin
✅ Monthly break-even target
Once these numbers are clear, pricing decisions become much easier. You’ll know how many hours, clients, or projects your business needs before it begins generating profit.
Common Break-Even Mistakes Service Businesses Make
Even when business owners understand the formula, small errors can lead to poor pricing decisions and cash flow problems. Here are the mistakes to avoid.
Ignoring Owner Compensation
Many owners leave their own salary out of the calculation.
This makes the break-even point appear lower than it actually is. The business may look profitable while the owner is effectively working without fair compensation.
The Fix: Include a realistic monthly owner salary in your fixed costs.
Treating Every Payroll Cost as Fixed
Not every labour expense is fixed.
Contractors, temporary staff, and project bonuses usually increase when client work increases.
The Fix: Separate recurring payroll expenses from project-specific labour costs before calculating contribution margin.
Forgetting Small Variable Costs
Payment processing fees, travel expenses, software licences, and project materials may seem minor.
Over dozens of projects, they can significantly reduce your contribution margin.
The Fix: Review your last 3 to 6 months of projects to identify every cost directly related to delivering client work.
Assuming Every Working Hour Is Billable
Very few service businesses can bill 100% of staff time.
Employees also spend time on:
- Sales
- Administration
- Training
- Team meetings
- Client communication
- Marketing
The Fix: Plan for a realistic utilization rate of 65% to 75% instead of assuming every paid hour generates revenue.
Never Updating the Calculation
Your break-even point changes whenever expenses or pricing change.
Annual software renewals, wage increases, rent adjustments, or higher contractor rates all affect the calculation.
The Fix: Review your break-even point every month and after any major pricing or cost changes.
Looking Only at Revenue
High revenue does not always mean high profit.
A business can double sales while earning less if costs rise even faster.
The Fix: Track contribution margin and break-even targets alongside monthly revenue.
Review your break-even calculation at least once each month.
A 5% increase in expenses or a small reduction in pricing can noticeably change the number of hours, clients, or projects needed to reach profitability.
Frequently Asked Questions
What is the break even point formula for service business?
The basic formula is:
Break-Even Point = Total Fixed Costs ÷ Contribution Margin
If you bill by the hour, the result is the number of billable hours needed each month before earning a profit. If you sell retainers or projects, the result is the number of clients or projects required to cover all costs.
How do I calculate contribution margin?
Subtract your direct variable costs from the amount you charge the client.
Formula
Contribution Margin = Selling Price − Variable CostsFor example, if you charge $200 per hour and your direct costs are $50, your contribution margin is $150 per hour.
Should I include my salary when calculating break-even?
Yes.
If you work full time in the business, your salary should be treated as a required business expense.
Including owner compensation gives you a more realistic break-even target and helps you set prices that support long-term growth.
What is considered a fixed cost?
Fixed costs are expenses that usually stay the same regardless of how many clients you serve.
Examples include:
- Rent
- Insurance
- Administrative salaries
- Accounting fees
- Software subscriptions
- Loan repayments
These expenses must be paid even during slower months.
How often should I recalculate my break-even point?
Review your numbers at least once each month.
You should also update the calculation whenever your pricing, payroll, rent, contractor costs, or other major expenses change.
Regular reviews help prevent unexpected cash flow problems.
Is break-even analysis useful for freelancers?
Absolutely.
Freelancers can use the same formulas to determine:
- Minimum monthly revenue
- Required billable hours
- Ideal pricing
- Income targets
- Sustainable workload
Knowing these numbers helps you avoid underpricing your services.
Conclusion
Understanding the break even point formula for service business gives you more than a financial calculation. It gives you a practical operating target.
Instead of guessing how many clients or projects you need each month, you can calculate the exact amount of work required to cover your costs and begin earning a profit.
Start by listing your fixed costs, calculating your contribution margin, and applying the appropriate formula for your business model. Then compare the result with your available capacity to confirm your goals are realistic.
Finally, revisit your break-even analysis regularly. Small changes in pricing or expenses can have a meaningful effect on profitability. Keeping your numbers up to date helps you make better decisions about pricing, hiring, and future growth.
Leave a Reply
You must be logged in to post a comment.